Credit card comparison Switzerland
Best credit card in Switzerland 2026
Free credit cards compared, with annual fee, foreign fees, cash withdrawal and interest of 8 well-known cards
 Updated on 15 November 2026 · Reading time approx. 9 minutes · by Helga Baechler, certified wealth advisor IAF
There are a lot of credit cards in Switzerland, and it is not easy to keep track. In this comparison I focus on what really matters for your wallet. Annual fee, costs abroad, cash withdrawals and interest. You will also see how the points systems work and which card I use myself.
Short answer
Which free credit card is worth it in Switzerland?
Four of the five cards compared have no annual fee, only the SWISS Miles & More Classic costs CHF 120. My number 1 is the Coop Supercard credit card. Since 12 May 2026 it no longer charges a separate foreign currency fee, just like the Migros Cumulus. With my code liebefinanzen you get 1’500 Superpoints (CHF 15) when you order it.* For cash, use a debit card from Yuh, neon or Zak instead, because most credit cards charge 3.75 % for withdrawals.
Quick check: which card suits you?
| Your situation | Best card |
|---|---|
| Everyday life in Switzerland, you often shop at Coop | Coop Supercard |
| You travel a lot and do not shop at Coop | Migros Cumulus |
| You fly regularly with SWISS or Lufthansa | Miles & More Classic |
| You want simple cash back instead of points | Cashback Card |
| You are unsure or only need a card now and then | Coop Supercard, free and easy to test |
Free credit cards in Switzerland: comparison table 2026
These are the best-known Swiss credit cards. Pay special attention to three costs. Purchases abroad, interest on instalments and fees for cash withdrawals.
| Coop Supercard (No. 1) | Migros Cumulus | Swiss Loyalty Poinz | SWISS Miles & More Classic | Cashback Cards Mastercard | |
|---|---|---|---|---|---|
| Voucher code | liebefinanzen = 1’500 Superpoints, apply* | ||||
| Rewards | Coop Superpoints | Migros Cumulus points | Cash credit | Air miles | Cash credit |
| Annual fee | CHF 0 | CHF 0 | CHF 0 | CHF 120 | CHF 0 |
| Issuer | TopCard Service AG | Migros Bank | Swisscard AECS GmbH | Swisscard AECS GmbH | Swisscard AECS GmbH |
| Paper invoice | CHF 1.95 | CHF 2 | CHF 1.95 | CHF 1.95 | CHF 1.95 |
| Purchases abroad | 0 %** | 0 %** | 2.5 % | 2.5 % | 2.5 % |
| Reminder fees | CHF 0 to CHF 60 (1st reminder free) | CHF 30 | CHF 30 | CHF 20 | CHF 30 |
| Cash in Switzerland | 3.75 %, min. CHF 5 | 2.5 %, min. CHF 5 (free at Migros tills up to CHF 1’000 per day) | 3.75 %, min. CHF 5 | 3.75 %, min. CHF 5 | 3.75 %, min. CHF 5 |
| Cash abroad | 3.75 %, min. CHF 10 | 2 withdrawals per year up to CHF 500 free, then 2.5 %, min. CHF 10 | 3.75 %, min. CHF 10 | 3.75 %, min. CHF 10 | 3.75 %, min. CHF 10 |
| Interest | 12 % | 10.4 % | 13 % | 13 % | 13 % |
| New PIN | CHF 10 | CHF 10 | CHF 10 | CHF 10 | not stated |
| Replacement card | CHF 20 | CHF 20 | CHF 25 | CHF 25 | CHF 25 |
| Limit | CHF 1’000 to CHF 10’000 | CHF 15’000 | CHF 10’000 | CHF 15’000 | CHF 10’000 |
**Coop Supercard and Migros Cumulus charge no separate foreign currency fee (Coop since 12 May 2026). The exchange rate they use includes a markup, which I estimate at approx. 1.5 to 3.5 %. Migros Cumulus checked on 3 November 2026 with the Migros Bank price list (version 09/2026). Coop Supercard checked on 3 November 2026 with the information from Coop and TopCard. The other cards were not rechecked. Fees and interest rates can change, so check the current conditions directly with the issuer.
Foreign fee at Coop and Migros
For a long time the Coop Supercard was only second choice abroad. Since 12 May 2026 the separate foreign currency fee is gone, so it is now on the same level as the Migros Cumulus. With both cards the markup is now part of the exchange rate. «0 % fee» therefore does not automatically mean the best rate. Abroad, pay in the local currency instead of CHF whenever you can.
What the cards really cost you: 3 examples
| Situation | Coop Supercard | Migros Cumulus | Swisscard cards | Miles & More |
|---|---|---|---|---|
| Holidays, CHF 3’000 spent abroad per year (annual fee plus separate foreign fee) | CHF 0* | CHF 0* | CHF 75 | CHF 195 |
| Withdrawing CHF 200 cash in Switzerland (fee per withdrawal) | CHF 7.50 | CHF 5.00 | CHF 7.50 | CHF 7.50 |
| Instalments, CHF 1’000 balance for one year (interest) | CHF 120 | CHF 104 | CHF 130 | CHF 130 |
*No separate foreign currency fee, the markup is in the exchange rate (estimated approx. 1.5 to 3.5 %). With the other cards the exchange rate comes on top of the 2.5 % fee. Simplified calculation with 10.4 %, 12 % and 13 % interest.
How to avoid credit card fees
- Always pay the full invoice. Instalments cost 10 to 13 % interest.
- Never withdraw cash with a credit card. Use a debit card instead.
- Choose an e-invoice instead of paper. You save approx. CHF 2 per month.
- Abroad, pay in the local currency and decline the conversion into CHF at the terminal.
- One free card is enough. More cards mean more to keep track of.
Best credit card in Switzerland 2026: my ranking
No annual fee, no separate foreign fee since May 2026, a simple Superpoints system and an issuer (TopCard/UBS) I have had good experiences with. For me, the Coop Supercard is the only credit card I recommend without reservation.
No. 1 of 5
Coop Supercard credit card
1’500 Superpoints free
- No annual fee
- No separate foreign fee since May 2026
- 1 Superpoint per CHF 1 at Coop and partners
Apply for the Coop Supercard →
Enter the code when you order and you get 1’500 Superpoints (CHF 15). *Advertising, affiliate link.
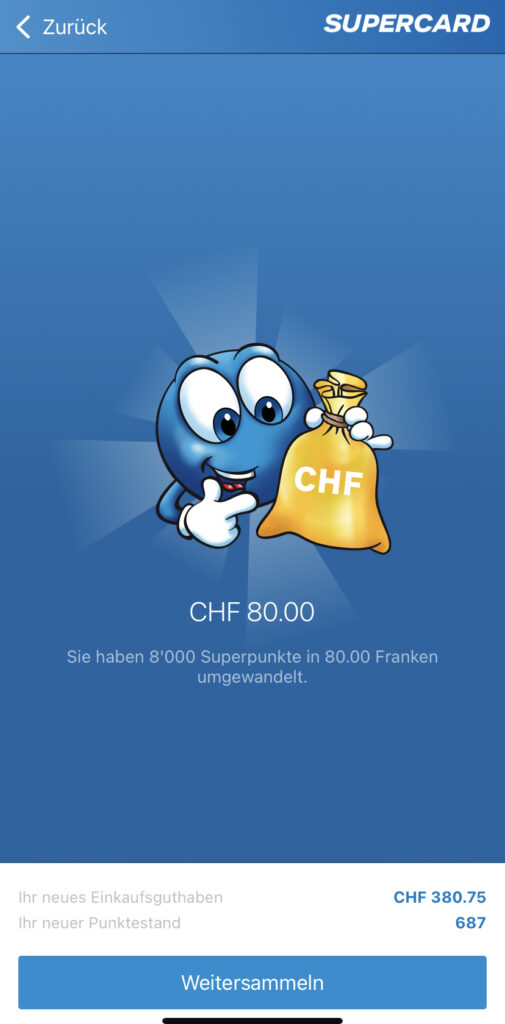
Example: what the Superpoints bring you
If you spend CHF 15’000 per year at Coop and partners, you collect 15’000 Superpoints (1 point per CHF 1). With another CHF 10’000 spent outside Coop you get approx. 3’333 more points (1 point per CHF 3). That makes approx. 18’333 points, worth approx. CHF 183 (100 points = CHF 1). Add the welcome bonus of 1’500 points (CHF 15) with the code liebefinanzen. All of it is free, because there is no annual fee. You can find all details in my Coop Supercard credit card review.
The other four cards are not bad, but each has a clear disadvantage compared to the Coop Supercard.
| Rank | Card | Disadvantage compared to Coop Supercard |
|---|---|---|
| 2 | Migros Cumulus | Same level on fees, but the rewards bring me personally less than Superpoints, because I shop at Migros less often. |
| 3 | Cashback Card (Swisscard) | 2.5 % foreign fee instead of 0 %, but simple cash back without converting points. |
| 4 | Swiss Loyalty Poinz | Also 2.5 % abroad, and the points can be redeemed in fewer places in everyday life than Superpoints. |
| 5 | SWISS Miles & More Classic | The only card with a CHF 120 annual fee. Only worth it if you really fly SWISS or Lufthansa regularly and use the miles. |
Other free credit cards 2026: Swisscard, Simply and Cashback Cards
I am often asked about three more cards without an annual fee. I do not use them myself, so they are not in my ranking. Here are the key facts anyway.
| Card | Annual fee | Foreign currency purchases | Bonus | Good for |
|---|---|---|---|---|
| Swisscard credit card (Visa) | CHF 0 | no separate fee, markup in the exchange rate | no cash back | a simple card for travelling |
| Simply Card Smart (Bonus Card, Cornèr Bank) | CHF 0 | 0.5 % | 1 point per CHF 1 | online shopping in euros and dollars |
| Swisscard Cashback Cards (Amex and Visa or Mastercard) | CHF 0 | 2.5 % | up to 1 % with the Amex | many CHF payments where Amex is accepted |
As of November 2026, information from the issuers. Cash withdrawals are expensive with these cards too, usually approx. 4 %. Check the current conditions directly with the issuer.
What to look for in a free credit card
1. Annual fee
Are the benefits, such as airport lounge access, really worth an annual fee? I avoid credit cards with an annual fee of CHF 100 or more, whatever the benefit.
2. Fees for payments abroad
Most credit cards add a percentage fee to purchases in foreign currency. Migros Cumulus and now also the Coop Supercard do without a separate foreign fee, but both build a markup of approx. 1.5 to 3.5 % into the exchange rate. Realistically, there is no true zero-cost card for abroad. The free Swisscard cards charge an explicit 2.5 %, which is too expensive for me. For holidays, the Swiss smartphone banks neon and Zak are more attractive. See my neobanks comparison.
3. Cash withdrawals
Never withdraw cash with a credit card, neither in Switzerland nor abroad. For cheap or free withdrawals, use a debit card from Yuh, Zak or neon, or the debit card of your bank.
| Debit card | Welcome bonus | Code |
|---|---|---|
| Yuh | CHF 50 + 250 Swissqoins | YUHLIEBE |
| neon | CHF 10 + free card | liebefinanzen |
| Zak | CHF 50 | ZAKLOV |
4. Interest on instalments
The biggest cost trap is interest. It applies when you do not pay the full amount within the payment period and choose instalments instead. If you bought a TV with the card and paid in instalments, the Coop Supercard would charge 12 % per year and the Swisscard cards approx. 13 %. Cembra Money Bank (CERTO, TCS, IKEA) currently charges 12 %, Cornèrcard up to 12 %. Always pay your invoice on time, otherwise it can lead to debt.
5. Costs for other services
Watch the costs for blocking the card, a new card, a forgotten PIN and paper invoices. Switch to the digital invoice in the app, set a push notification for the payment deadline and use the chat instead of the expensive hotline.
6. Cashback and rewards
A good rewards system matters to me, but it has to be simple and pay out regularly. I grew up shopping at Coop and try to maximise my Superpoints, so the Coop Supercard is my number 1, for everyday life and now also abroad.
7. Insurance
Some cards include insurance. I find these benefits too opaque, and it is unclear whether they really pay in case of a claim. That is why I do not cover them here.
8. Visa, Mastercard or American Express?
If you live in Switzerland and travel a few times a year, choose Visa or Mastercard. American Express is still not accepted everywhere in Switzerland. If you travel a lot, an Amex can be worth it.
My favourite free credit cards
I now limit myself to two credit cards. The Coop Supercard for all purchases in Switzerland and now also abroad, with code liebefinanzen for 1’500 Superpoints.* And the Migros Cumulus as a backup, also without a separate foreign currency fee.
Which credit cards gave me bad experiences?
Unfortunately I had bad experiences with the cards of Cembra Money Bank. I occasionally used the IKEA credit card and the CERTO credit card. Having all Cembra cards in one app is practical, but the app did not work properly. It did not show me the monthly invoices, and push notifications and paper invoices were not reliable either.
What it cost me
I had to pay reminder fees of over CHF 30 several times, plus interest. That cost me more than CHF 100, even though I used the cards rarely and for small amounts. In autumn I cancelled both cards by filling in the PDF form by hand and sending it by post. That worked well, and now I focus only on my top cards.
Applying for a credit card: requirements
| Point | What applies |
|---|---|
| Minimum age | 18 with most issuers, additional cards partly from 16 |
| Residence | private individuals living in Switzerland |
| Income and credit check | a regular income is checked, the limit depends on your creditworthiness |
| Process | fill in the online form, confirm your identity by video or at a post office |
| Duration | after approval the card usually arrives by post within approx. 7 working days |
Applying is free and non-binding for all cards in this comparison, and you can cancel any time free of charge. New in Switzerland? My money checklist for expats shows the order in which to open your accounts.
Best credit card Switzerland: FAQ
What is the best credit card in Switzerland?
For most people the Coop Supercard credit card is the best choice. No annual fee, no separate foreign fee since May 2026 and Superpoints on every purchase. With the code liebefinanzen you get 1’500 Superpoints for free. If you often fly SWISS, a miles card can be worth a look.
Are there really completely free credit cards in Switzerland?
Yes, several issuers permanently waive the annual fee, for example Coop Supercard and Migros Cumulus. Still watch the extra costs such as cash withdrawals, interest, paper invoices and the effective exchange rate.
Which free credit card has no foreign transaction fee?
Both the Migros Cumulus and, since May 2026, the Coop Supercard charge no separate foreign currency fee. With both cards, however, an estimated exchange rate markup of 1.5 to 3.5 % is included in the rate itself.
Should I withdraw cash with a credit card?
No, it is expensive with almost all credit cards, usually 3.75 % of the amount. Use a debit card or a smartphone bank like Yuh, neon or Zak instead.
What happens if I do not pay my credit card bill on time?
You pay interest, depending on the issuer between approx. 10 % and 13 % per year. Always pay your invoice in full and on time.
Can expats get a Swiss credit card?
Yes, if you live in Switzerland and have a regular income. The issuer checks your creditworthiness. If you have just arrived, start with a Swiss bank account and a debit card, then apply for the credit card.
Conclusion
A free credit card is only really free if you avoid the extra costs. Always pay the full invoice, never withdraw cash with the credit card and skip the paper invoice. For me the Coop Supercard is number 1 and the Migros Cumulus my backup. For cash and holidays I use smartphone banks like Yuh, neon or Zak.
Read more
- Coop Supercard credit card review
- Neobanks Switzerland comparison
- Bank account for expats in Switzerland
- All Swiss promo codes
*Advertising, affiliate links. If you apply for a card via a link or code, I may receive a small commission. There are no extra costs for you. No financial advice.