Health insurance 2027
Compare Swiss health insurance independently
Why Comparis is not neutral, and what to do with the premium you save
 Updated on 14 November 2026 · Reading time approx. 4 minutes · by Helga Baechler, certified wealth advisor IAF
Swiss health insurance premiums are rising by 5 % on average in 2027. Many people are now comparing on Comparis. But Comparis is not a neutral comparison; it is a broker.
Here you will see how to compare your health insurance truly independently, and what to do with the money you save.
Where can I compare Swiss health insurers independently?
On priminfo.admin.ch, the federal government’s official premium calculator. It is anonymous, ad-free and shows all insurers. Your cancellation must reach your insurer by 30 November 2026, so it is best to send it by registered mail by mid-November.
Premium figures according to the FOPH announcement of 29 September 2026, checked on 3 November 2026. For adults, the average premium in 2027 is CHF 487.60 per month.
⚖️ Comparing health insurance independently: priminfo vs. Comparis
Comparis is registered with FINMA as an insurance intermediary. The premiums shown are correct, but Comparis earns money when you sign up.
| priminfo.admin.ch | Comparis & co. | |
|---|---|---|
| Operator | Federal Office of Public Health | Private brokers |
| Commissions | ✓ None | ✕ Up to CHF 70 per contract |
| Ranking | ✓ By price only | ✕ Partly paid |
| Data | ✓ Anonymous | ✕ Quote only with contact details |
| Good for | Basic insurance | Supplementary insurance |
Watch out
There are fake calculators with a Swiss cross that collect data. The only official one is priminfo.admin.ch.
🔍 How to compare with priminfo
Enter where you live. The premium depends on your region.
Check accident cover. If you work at least 8 hours a week, your employer covers accidents. Then exclude accident cover.
Choose deductible and model. Compare family doctor, HMO and telemedicine models too.
Sort by price. Note the two or three cheapest.
Official premium calculator
priminfo.admin.ch by the FOPH. All 2027 premiums, anonymous and with cancellation templates.
The benefits of basic health insurance are the same everywhere. So you simply pay less for the same cover.
💸 Where you save the most
| Lever | Effect | Suits you if |
|---|---|---|
| Cheaper insurer | Same benefits, lower price | Always |
| Alternative model | Usually much cheaper | You call first or go to your family doctor first |
| Deductible CHF 2’500 | Premium drops sharply | You are healthy and have savings |
| Without accident cover | A few percent less | You are employed at least 8 hours a week |
- High deductible only with a cushion. How much you need is shown by the emergency fund calculator (German). How long your cushion lasts without a salary is shown in the reserves calculator (German).
- Check premium subsidies. On a low income, you may be entitled to them.
🔄 Switching in 4 steps
Compare with the same deductible and the same model.
Sign up directly with the insurer, without a broker.
Cancel by registered mail. The cancellation must reach your insurer by 30 November 2026; the postmark does not count. So it is best to send it by mid-November.
Done. From 1 January you are seamlessly covered by your new insurer.
Important
Only cancel your supplementary insurance once the new insurer has accepted you in writing. Basic and supplementary insurance may be with different insurers.
📈 Investing what you save
From January, set up the difference as a standing order into an ETF savings plan. That turns a saving tip into wealth.
| Per month | 10 years | 20 years | 30 years |
|---|---|---|---|
| CHF 50 | CHF 7’764 | CHF 20’552 | CHF 41’613 |
| CHF 100 | CHF 15’528 | CHF 41’103 | CHF 83’226 |
| CHF 150 | CHF 23’292 | CHF 61’655 | CHF 124’839 |
Example with a 5 % return per year, before fees and taxes. Not guaranteed; ETFs can lose value. Your own figures in the ETF savings plan calculator (German).
- Emergency fund first, especially with a high deductible.
- Broad world ETF to start with. More in investing for beginners.
- Choose a provider with the ETF savings plan comparison (German).
- Or pillar 3a with securities, never with insurance.
Where to invest your premium savings
For complete beginners, I recommend the Yuh app. I deliberately have no affiliate links for health insurers.
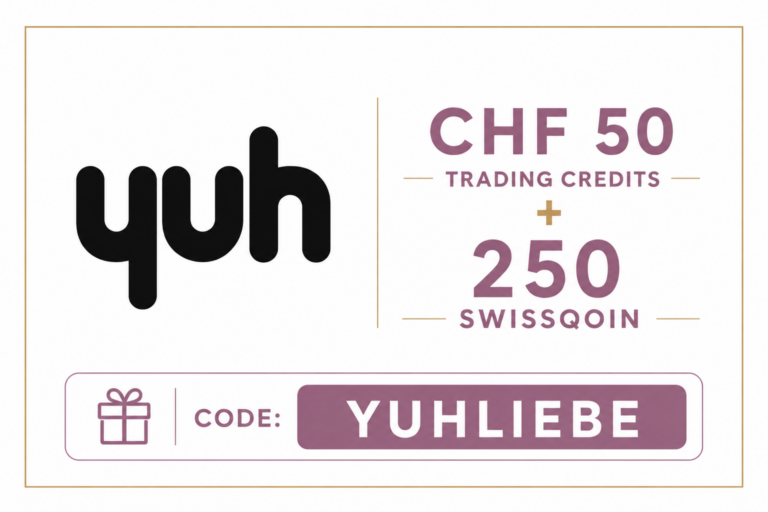
Yuh
CHF 50+ 250 Swissqoin for free
- Account, ETF savings plan and 3a in one app
- Savings plan even with small amounts
- Enter the code when signing up in the app
Swiss residency required. *Advertising, affiliate link.
finpension
Low-cost index fund strategies for 3a and investing. CHF 25 fee credit. More about the finpension code
findependent
Robo-advisor with ETFs and automatic rebalancing. CHF 20 bonus, only one findependent code per person. More about the findependent code (German)
You will find all codes in my code overview. Want more? Read health insurance premiums 2027 and pharma stocks (German).
🙋 FAQ
Is Comparis independent?
No. Comparis is registered as an insurance intermediary and receives commissions, in basic insurance up to CHF 70 per contract.
Which comparison is neutral?
priminfo.admin.ch by the Federal Office of Public Health. Official, anonymous and with all insurers.
By when can I switch?
The cancellation must reach your insurer by 30 November 2026; the date of receipt is what counts. The switch takes effect on 1 January 2027.
Is a cheaper insurer worse?
No. The benefits of basic health insurance are the same everywhere by law.
What should I do with the money I save?
Set it up as a standing order into an ETF savings plan or a 3a with securities. CHF 100 a month can grow to over CHF 80’000 in 30 years at a 5 % return, without guarantee.
Verdict
Compare your basic health insurance on priminfo.admin.ch, not with a broker. The benefits are the same everywhere; you just pay less. Cancel in time so that your letter reaches your insurer by 30 November 2026. And invest the premium you save automatically every month.
Read more
Sources: FOPH, premiums 2027 · FOPH, Priminfo · Beobachter · SRF · finews. Premiums checked on 3 November 2026.
*Advertising, affiliate links; they cost you nothing extra. This article is for general information only and is not investment or insurance advice.